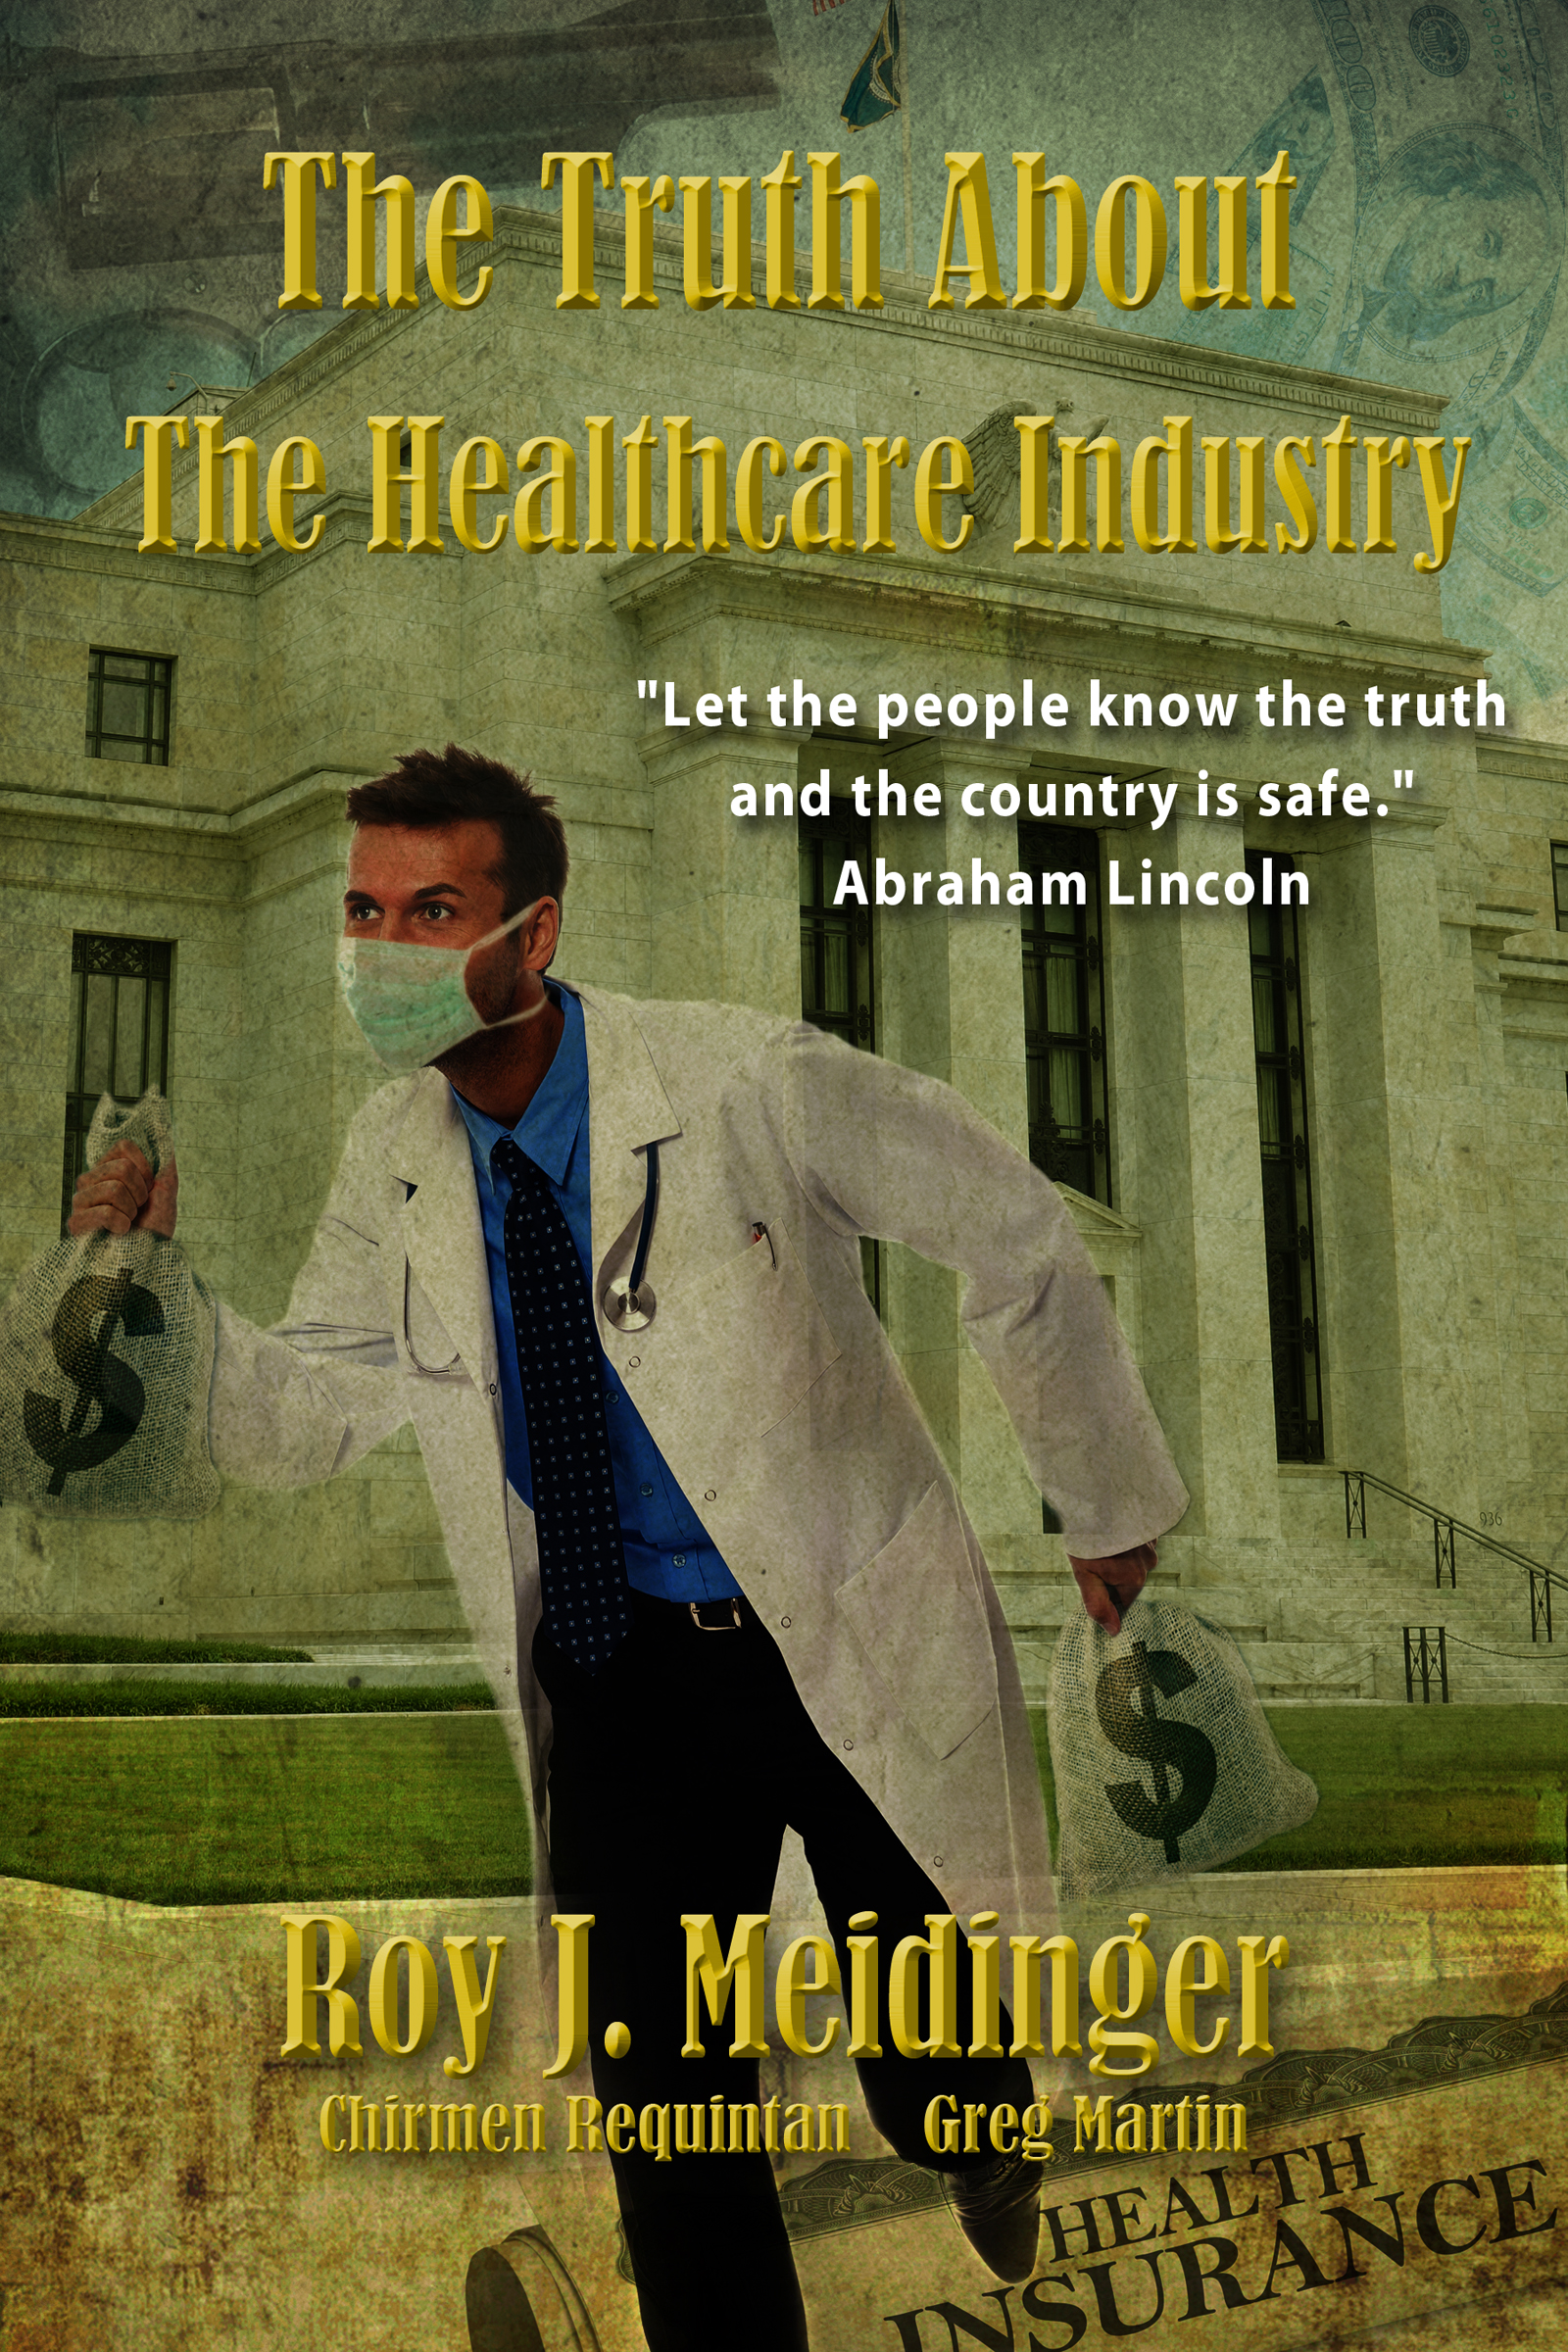
Washington, D.C, District of Columbia Sep 15, 2022 (Issuewire.com) - In the book, The Truth About the Healthcare Industry, the author explains why the United States healthcare system went from a low-cost competitive industry to a high-cost Oligopoly because of the lack of understanding of the accounting practices of providers and insurance companies.
The United States' healthcare costs are the greatest of all the industrial countries. The providers' tremendous operating expense on the private business side is the payment of kickbacks to the insurance companies, allowing the providers to have unfettered access to their insured members. The patient is the customer; therefore, the patient chooses the medical provider. Usually, the patient selects the provider that costs the least. However, when a patient is insured, an in-network provider's co-payments are much lower in cost than an out-of-network provider. This is because the insurance companies choose the in-network providers, not on their lower standard charges but on the kickbacks the insurance companies pay them. To control costs, Federal and State legislators have made kickbacks illegal in the healthcare industry, so the question is how the kickbacks have remained hidden for so long and who is responsible for finding the kickbacks.
Two central contracts are in play on the private business side of the Healthcare Industry. The contract between the patient and the provider establishes who the customer is and is the one that creates the income for the provider. The patients' bills list the standard charges, with no discounts, and when the statement is issued, these amounts determine the gross income for tax purposes. When a private-pay patient is insured, a second contract is created between the provider and the insurance company. This is where the real problem is. The IRS believes the insurance company is the customer because it pays the patient's bill.
The insurance company is not the customer; it is not entitled to any discounts or has any right to change the price of the medical bills for services or goods. A close examination of the insurance company's contract shows that not only is it being paid to refer patients to the provider but to charge an insured member an additional co-payment if it goes to a provider that is not recommended. The recommended providers fall into the category in-network, and the category the insured member is punished for using is labeled out-of-network.
At the end of the tax year, the provider must reconcile its income to determine its profits for tax purposes. Therefore, the provider will deduct its operating expenses, bad debts, and canceled debts from its gross income. The amounts not collected from the third-party payers would usually be considered canceled debts, and information tax returns, 1099C returns, sent to the IRS so the insurance companies would include the forgiven debt in their income taxes, but the providers do not. So, the amounts not collected and the canceled debt payments are actual operating expense deductions.
The providers and insurance companies have a significant problem with how to hide the kickbacks. The usual business practice is for the customer to pay the bill fully and then the provider to pay a kickback to the person referring the customer; this method would have allowed easy detection of the kickbacks. In the healthcare industry, rather than pay cash, the providers pay the insurance companies with canceled debts. The providers should have recorded these payments as operational expenses, and the insurance companies should have called them forgiven debt income. This classification of these amounts would have alerted the IRS auditors to the illegal payment of kickbacks. Instead, the providers and insurance companies utilized the contra account contract adjustments on the government business side. This contra account is created for only government business accounting. The government needed to know the amount the private pay patients were being charged to recalculate its reimbursement amounts for Medicare and Medicaid annually. The difference not collected was allowed to be deducted to enable the providers to reconcile their gross income and determine the actual profit.
In the healthcare industry, State and Federal governments do not allow kickbacks for referring patients. Therefore, the providers cannot deduct the payments from gross income. Instead, the providers should list them on their income tax returns, 1120 or 1120s, for-profit corporations, and 990T income tax returns for not-for-profit corporations. The law calls for the not-for-profit corporation's income status to be revoked for the illegal practice of paying kickbacks. The problem is whether the IRS will stand up and say it made a significant error, collect the unpaid taxes or allow the industry to continue the unlawful practice and the cover-up.
The Truth About The Healthcare Industry is available on Amazon Kindle.
Media Contact
Roy Meidinger RoyJMeidinger@comcast.net 9547909507 14893 American Eagle Ct. http://None